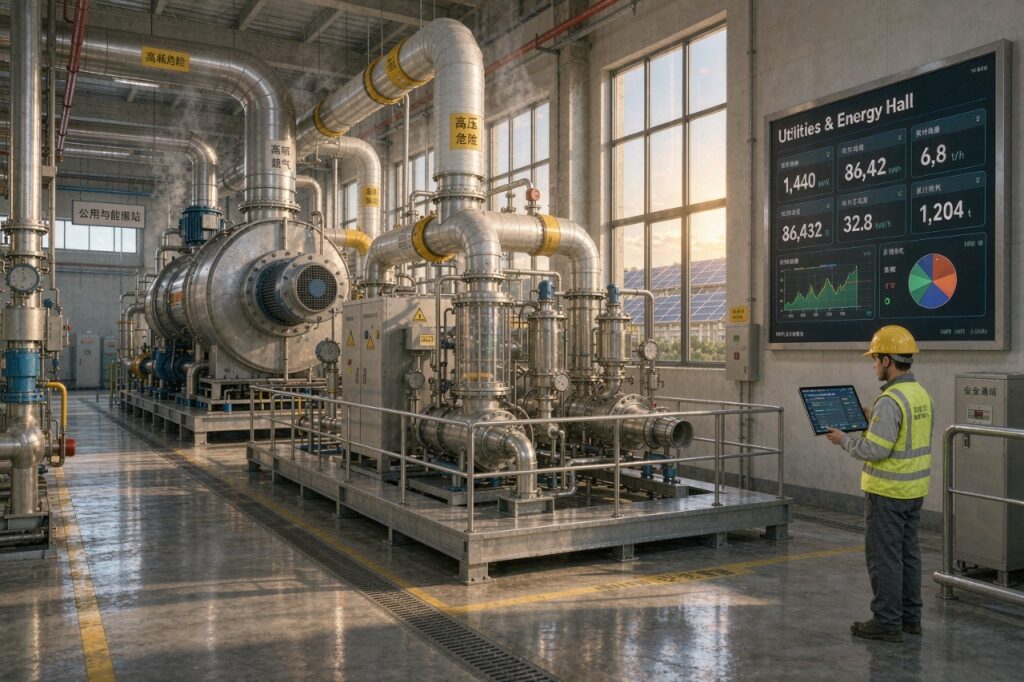
The Energy Line: MVR Steam Recovery, Rooftop Solar and the Per-Tonne Cost Reset Facing Every Soap Plant
- Energy is a process-function problem, not a utility bill. Saponification and mixing, spray drying and packaging lines together absorb the large majority of a soap or detergent factory’s electrical load — which is why the levers sit on the machine spec sheet, not with the power retailer.
- MVR is the biggest single steam lever. Mechanical vapour recompression cuts fresh-steam consumption by roughly 90% against a single-effect evaporator, at the price of a 2–3× higher capex and a payback that only works in continuous duty.
- The cheapest steam is the steam you never need. Semi-concentrated saponification routes that deliver soap at 12–16% moisture can cool directly, eliminating the vacuum drying stage altogether.
- Rooftop PV fits soap plants unusually well. Because saponification, mixing, drying and packaging all run in daylight, self-consumption reaches 80–90% and solar can offset 30–45% of factory electricity with a 4–6 year payback.
- The policy floor is rising. From 2026 the EU begins phasing out free emission allowances, and at an allowance price near €65/tCO2 the carbon component of industrial electricity bills can reach up to 9% in the most carbon-intensive power systems.
- Q4 is the contracting window. Energy specifications written into equipment orders this quarter will set operating cost for the next 10–15 years of asset life.
1. Why Q4 2026 Is the Energy Cost Reset
For three years the soap industry’s cost conversation has started and ended with palm oil. That framing is now incomplete. Two structural changes land in the same contracting window as Q4 energy negotiations:
First, the phase-out has begun. From 2026, free emission allowances under the EU Emissions Trading System start being withdrawn — a 2.5% annual reduction in 2026 and 2027 for eligible producers in CBAM-covered sectors. At an EU allowance price near €65 per tonne of CO2, the carbon-cost component of industrial electricity bills can reach up to 9% in the most carbon-intensive power systems. The Commission also advanced its scheduled ETS review to July 2026, a sign of how contested the price signal has become.
Second, member states are intervening directly on industrial power prices — which tells equipment buyers something useful about where the cost pressure actually sits:
| Policy signal (2026) | Magnitude | What it means for a soap line |
|---|---|---|
| EU ETS free-allocation phase-out | −2.5%/yr in 2026 and 2027 | Electricity and fuel become a rising, priced line item rather than a fixed utility charge |
| Carbon cost exposure | Up to 9% of industrial power bills at €65/tCO2 | Favours lower-enthalpy processes: MVR over multi-effect, heat recovery over new boiler capacity |
| German industrial power support | €0.05/kWh from 2026, ~2,000 energy-intensive firms, est. €3–5 bn over three years | Electrification of process heat becomes economically rational in one of Europe’s largest HPC markets |
| Italy 2026 energy decree | >€3 bn; ETS cost reimbursement to gas-fired generation | Decouples wholesale power from the carbon price — volatility, not a clear direction |
| CBAM compliance phase | In force since 1 Jan 2026; first declaration and surrender 30 Sept 2027 for 2026 emissions | Downstream-scope extension is a live legislative proposal — emission data capture on the line is the cheap hedge |
Sources: Allianz Trade, EU ETS analysis (2026); International Carbon Action Partnership, CBAM compliance phase briefing; Irish EPA CBAM guidance.
Add the calendar: PACK EXPO Las Vegas runs 29 September to 1 October with sustainability and automation as two of its four organising themes, and Q4 capital budgets close shortly afterwards. Equipment specifications agreed in this window will be the ones that operate in 2027 — and for the next decade after that.
2. Where the Energy Actually Goes
Energy spend at a soap, detergent and household-chemical plant is not spread evenly, and it is not spread the way most procurement teams assume. Published energy audits from Southeast Asian production bases — the region that hosts a large share of multinational home-care capacity — give a consistent profile:
| Process function | Share of factory electricity | Typical equipment and operating pattern |
|---|---|---|
| Saponification & mixing | 25–35% | 5–20 t kettles or continuous loops holding 80–100 °C on steam or electric heat; ribbon, paddle and ploughshare mixers with 30–150 kW drives |
| Drying tower / vacuum drying | 20–30% | 15–30 m towers atomising slurry into 200–350 °C air; fans, slurry pumps, cyclones and bag filters draw 200–500 kW and run 16–24 h |
| Packaging lines | 15–20% | Stamping, wrapping, cartoning and case packing of bars; weighing, bagging and sealing of powders; lines running 200–600 units/min |
| Warehouse & cooling | 10–15% | 15–30 °C holding for liquids and softeners, temperature-controlled oleochemical storage, forklift charging |
| Water treatment & utilities | 5–10% | Aeration, clarifiers, filtration and scrubber duty on high-BOD/COD wash water; boiler feedwater pumps, compressed air, lighting |
Sources: CapSolar Thailand, soap/detergent factory energy audit profiles (2026); published soap-industry benchmarking.
Two conclusions follow. The first is arithmetic: saponification and mixing (25–35%), drying (20–30%) and packaging (15–20%) sum to somewhere between 60% and 85% of the electrical load, so a plant planning around a working mid-figure of 70% is planning around the right number. The second is strategic: that 70% is governed by machine design — the enthalpy of the drying route, the sizing of agitator drives, the duty cycle of wrapping lines — not by tariff negotiation.
Aggregate energy intensity across these stages typically lands in the 180–320 kWh per tonne band of finished soap, with the spread explained mostly by moisture handling: plants that evaporate large volumes of process water sit at the top of the range, plants that arrive at the plodder already dry sit at the bottom.
3. The Steam Decision: MVR and the Heat-Recovery Ladder
If drying is where the energy is consumed, evaporation is where it is lost. The conventional answer has been multiple-effect evaporation — reuse the vapour from one effect as the heating medium for the next. The 2026 answer, increasingly, is mechanical vapour recompression (MVR): a compressor takes the low-grade secondary vapour that would otherwise be condensed and dumped, raises its pressure and temperature by 8–20 °C, and returns it to the calandria as the heating medium. The heat does not leave the loop; only the compressor work enters it.
| Evaporation route | Fresh steam per tonne of water | Electrical load | Thermal efficiency | Capex & payback |
|---|---|---|---|---|
| Single-effect | ≈1.1 t (baseline) | Vacuum duty 12–18 kWh/t | 45–60% | 1× reference |
| Triple-effect | ≈0.35 t (−68%) | Vacuum duty 12–18 kWh/t | 45–60% | Large vessel train, big footprint |
| MVR | 0.05–0.10 t (−≈90%) | 30–80 kWh/t compressor work; vacuum duty falls to 1.5–3 kWh/t | >92% | 2–3× capex; 2–4 yr payback, faster at scale |
Sources: MVR technology reviews and retrofit case data (2026); China Energy Conservation Association industrial equipment survey (Nov 2025); mechanical industry vapour-recompression test data (Jan 2026). Figures originate in adjacent process industries — chemical, food, pharmaceutical and effluent concentration — and should be treated as directional for soap duty.
Retrofit data from those adjacent industries shows why MVR has moved from novelty to standard option. Documented projects report fresh-steam consumption falling from 0.80 t per tonne of water to 0.07 t in one high-salt effluent retrofit, and from 0.32 t to 0.03 t in another; a 10 t/h installation cut annual steam spend by roughly 91%, from about RMB 2.8 million to RMB 0.25 million, with payback commonly quoted at two to three years where steam is expensive relative to power.
MVR is not free money, and the constraints matter more than the headline. It pays in continuous duty above roughly 5 t/day of evaporation; it does not pay in batch operation or where electricity is priced well above steam. High-viscosity or scale-forming feeds degrade heat transfer and require chemical cleaning on a 3–6 month cycle, compressor vibration typically held under 4 mm/s, and operators trained well enough to protect the rotating core of the system. Insulation is the cheap companion measure: an industrial audit of unoptimised evaporator trains put avoidable pipe-and-shell heat loss at 18–22% of total thermal input, with nano-insulation upgrades reported to cut loss to roughly 4.6% at a payback under one year.
The second lever is dryer avoidance. Jet-style and semi-concentrated saponification routes allow soap to be produced directly at low moisture — on the order of 12–16% water — so it can be cooled on chill rolls and sent to the plodder without ever entering a vacuum drying plant. Minimum steam consumption for such a plant is quoted at approximately 100 kg of steam per hour for every 1,000 kg of soap produced per hour, and the saving is not the efficiency of a dryer but the absence of one. A conventional semi-boiled plant, by contrast, lands at 58–60% total fatty matter with 28–30% water, and therefore pays to evaporate water it deliberately added.
4. The Electricity Decision: Why Rooftop PV Fits Soap Plants
Soap and detergent factories have an unusual generation profile match: their heavy loads are diurnal. Saponification, mixing, drying and packaging all run during the day, leaving a low night base load made up of warehouse cooling, water treatment and security. The consequence is a high self-consumption rate — most of the solar electricity generated is used on site rather than exported at minimal credit.
| Rooftop PV parameter | Typical value | Why it holds |
|---|---|---|
| System size | 200 kWp – 5 MWp | Scales with roof area; needs no process redesign |
| Share of factory electricity offset | 30–45% | Achievable without battery storage, because generation overlaps load |
| Self-consumption rate | 80–90% | Daytime-only production schedule captures the full tariff differential |
| Peak-demand charge reduction | 15–30% | The 08:00–10:00 simultaneous startup of drying, mixing and packaging lines coincides with the solar ramp |
| Payback | 4–6 years | Before any carbon value; improved where demand charges are ratcheted monthly |
Source: CapSolar Thailand, soap and detergent factory solar feasibility profiles (2026).
There is a compliance dividend on top of the arithmetic. Multinational home-care groups have committed to 100% renewable electricity by 2030 (Unilever and Procter & Gamble) and to carbon neutrality by mid-century (Lion). Those commitments flow down the supply chain as reporting obligations — supplier Scope 1–3 disclosure, environmental scorecards, and EU CSRD scope 3 expectations for anything exported into Europe. On-site generation is simultaneously the cheapest emission to remove and the most visible line in an audit file.
5. What the Benchmarks Look Like: Two Unilever Case Studies
The clearest published evidence that energy work pays comes from the two ends of Unilever’s manufacturing footprint — a 19th-century British campus rebuilt around automation and renewable power, and a 1960s Bangladeshi soap and home-care site that has spent fifteen years grinding down consumption.
| Dimension | Port Sunlight, UK | Kalurghat, Bangladesh |
|---|---|---|
| Investment | £150 m / USD 201 m home-care and logistics programme (2026) | Continuous efficiency programme against a 2010 internal baseline |
| Energy performance | New distribution centre runs on 100% renewable energy; capsule output rises from ~660 to over 2,000 units/min | Energy consumption down 31% — about 1.61 million GJ saved; roughly 90,560 t CO2 avoided, a 32% reduction |
| On-site generation | Solar panels, industrial heat pumps and solar-reflective paint; ~2,000 m of conveyors, eight 30 m stacker cranes | 100% renewable electricity since 2021 via certificates, with an expanding 1 MW rooftop array; a 785 kWp rooftop plant added by a third-party developer |
| Adjacent outcomes | Primary logistics down an estimated 27%; about 827 t CO2 avoided per year; ~13,600 t handled weekly | Water use down 33% (2,763 million litres) via condensate recovery and rainwater harvesting; zero waste to landfill since 2014 |
Sources: HPC Middle East & Africa (28 May 2026); CibusLink (2026); The Daily Star, Unilever Bangladesh industrial efficiency feature (2026); Textile Today, 785 kWp rooftop inauguration.
Read together, the two cases bracket the practical range. Port Sunlight shows what new capital can buy when energy, automation and logistics are designed as one system. Kalurghat shows what disciplined measurement and incremental retrofit deliver over time — and note the overlap: condensate recovery, heat recovery and rooftop generation appear on both lists. Those are equipment decisions, and both are available to a plant that does not have USD 200 million to spend.
6. The Retrofit Ladder: Sequenced by Payback, Not by Fashion
Energy projects fail when they are bought as a bundle. The working order is by measure-then-recover-then-regenerate, because each step makes the business case for the next:
| Step | Measure | What it changes | Indicative profile |
|---|---|---|---|
| 01 | Sub-meter every major consumer — reactor, dryer, compressor, packaging hall | Turns energy into a managed KPI; nothing can be optimised before it is measurable | Lowest cost, fastest return; prerequisite for everything below |
| 02 | Insulation upgrade on vessels, pipelines and dryer shells; condensate recovery | Attacks the 18–22% avoidable thermal loss that unoptimised trains routinely carry | Reported paybacks under one year at scale; no process risk |
| 03 | Heat recovery on compressors, vacuum systems and dryer exhaust | Recovers low-grade heat for wash water, CIP and preheating duty | Moderate capex, no change to the chemistry |
| 04 | MVR feasibility study where evaporation exceeds ~5 t/day | Replaces fresh steam with compressor work; the single largest steam reduction available | 2–3× capex of the equipment it replaces; 2–4 year payback in continuous duty |
| 05 | Rooftop PV sized to the daytime load, with demand-charge-aware scheduling | Offsets 30–45% of electricity and cuts the morning startup spike | 4–6 year payback; shorter where grid tariffs are high |
7. Q4 2026 Specification Checklist: Energy-Ready Equipment
| # | Specification | Why now |
|---|---|---|
| 01 | kWh per tonne and kg steam per tonne written into the acceptance test, not just output rates | Energy performance becomes a contractual obligation for the asset’s 10–15 year life |
| 02 | Sub-metering points designed in at every major consumer, with data exported to MES/SCADA | Also the raw material for Scope 2 reporting and customer sustainability scorecards |
| 03 | MVR-ready evaporator configuration, or a documented upgrade path to one | Retrofit is far cheaper than replacement if the calandria and vapour ducting are specified for it |
| 04 | Heat-recovery interfaces on dryer exhaust, vacuum system and compressor cooling | Adds wash-water and CIP preheating without touching the soap chemistry |
| 05 | Condensate recovery and insulation class specified to limit avoidable thermal loss | Addresses the 18–22% loss figure that dominates unoptimised plants |
| 06 | Dryer-avoidance option: semi-concentrated route with chill-roll cooling where the formulation allows | Eliminates the single most energy-intensive stage instead of optimising it |
| 07 | Solar-ready switchgear: reserved roof area, cable routes and demand-charge-aware load sequencing | Costs almost nothing at build stage and removes the main barrier to later PV |
| 08 | Multi-format feedstock and moisture tolerance at the reactor | Feedstock volatility and energy cost are managed by the same instrument — flexible process control |
Bottom Line
Energy has spent a decade as a background line in soap plant cost models. In Q4 2026 it is being repriced from two directions at once: carbon policy is withdrawing the free allowances that shielded industrial power, and the technology to cut steam demand by an order of magnitude — MVR, heat recovery, dryer avoidance — is now commercially standard rather than experimental.
The practical consequence for equipment buyers is that energy performance belongs in the purchase specification, alongside throughput and bar quality. A line that quotes output per hour but not steam per tonne and kilowatt-hours per tonne is quoting an incomplete machine.
The plants that will look structurally cheap to operate in 2030 are not the ones buying the largest evaporator. They are the ones that measured first, recovered second, and only then bought generation — in that order, because that is the order in which the money comes back.
Data Sources: Allianz Trade, “Signal without response: why the EU ETS needs resolve, not redesign” (2026); International Carbon Action Partnership, EU CBAM compliance-phase briefing; Irish Environmental Protection Agency, CBAM guidance; Enerace, CBAM 2026 cost mechanics; CapSolar Thailand, “Solar Energy for Soap, Detergent & Household Chemical Factories in Thailand” (2026); Soap World, JET saponification plant technical documentation; MVR evaporation technology reviews and retrofit case data (2026, including China Energy Conservation Association industrial equipment survey, Nov 2025, and mechanical-industry vapour-recompression test data, Jan 2026); HPC Middle East & Africa, Unilever Port Sunlight investment (28 May 2026); CibusLink, Port Sunlight programme report (2026); The Daily Star, Unilever Bangladesh industrial efficiency feature (2026); Textile Today, 785 kWp rooftop solar inauguration for Unilever Bangladesh; PW Consulting and Accio soap equipment market data (2026); PMMI PACK EXPO Las Vegas 2026 show materials. Energy intensities and payback ranges are compiled from published audits and vendor documentation; they are indicative and vary with tariff structure, duty cycle and site configuration.
© 2026 STING Industry · Published as draft for editorial review · Industrial soap equipment insights for global manufacturers.